Nissan CPO Financing vs Used Car Loans in Everett, WA
Why Nissan Certified Pre-Owned financing rates differ from standard used-car loans in Everett, WA — the mechanism, the tiers, and what shoppers should expect.
Nissan Certified Pre-Owned (CPO) financing through Nissan Motor Acceptance Company (NMAC) typically carries lower, promotional-style rate tiers than a standard used-car loan from a bank or credit union — because NMAC prices CPO loans as a captive-lender incentive to move inspected, warrantied Nissan inventory, while a generic used-car loan is priced purely on the lender's risk model for a non-certified used vehicle. The practical result for Everett, WA shoppers: a 2024 Nissan Rogue bought as CPO is often financed on a different rate sheet than the same car bought used from a non-franchised lot, even with identical credit.
What is the core mechanism behind the rate difference?
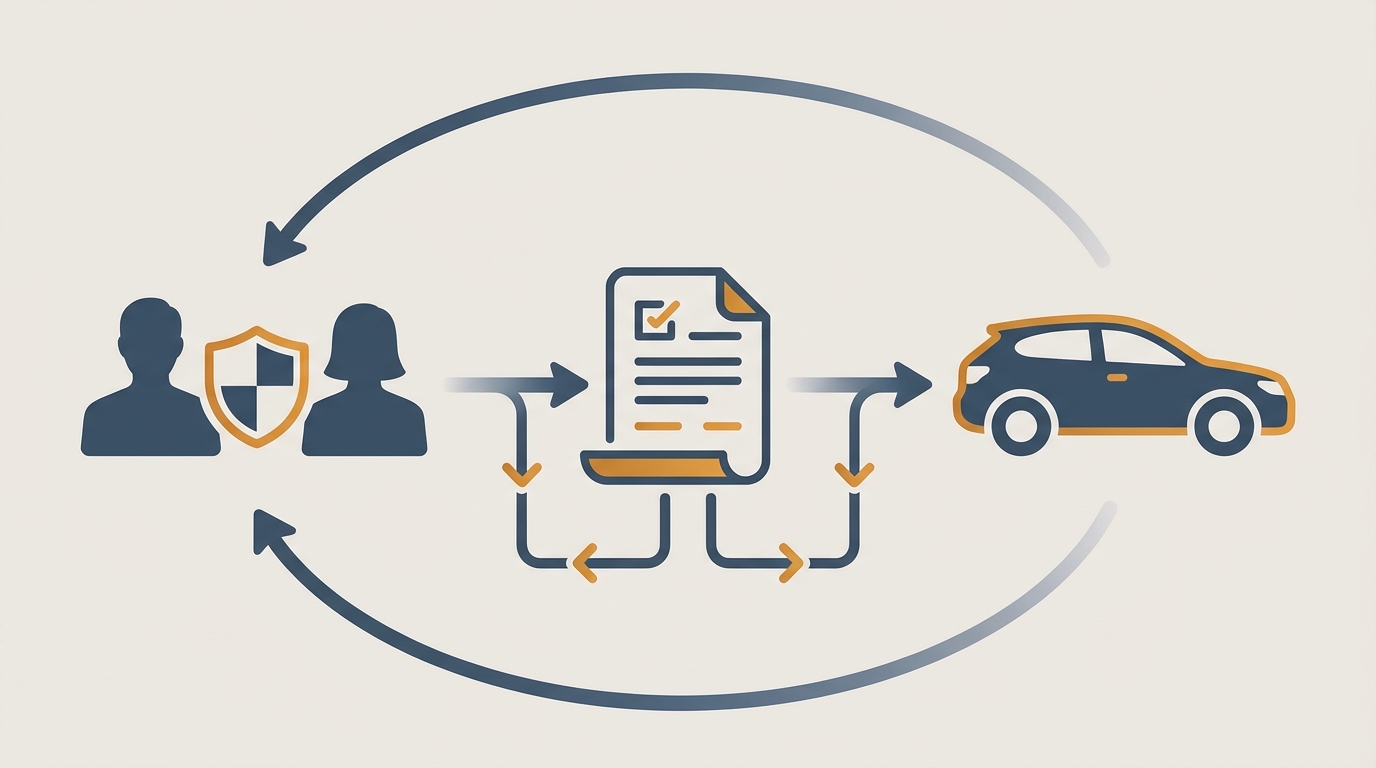
The rate gap exists because two different lenders are solving two different problems. NMAC, Nissan's captive finance arm, uses subvented CPO rates as a manufacturer-funded sales tool tied to certified inventory — the automaker effectively subsidizes the rate to protect residual values and reward buyers who choose an inspected, warrantied vehicle. A credit union or bank writing a used-car loan has no such incentive and prices purely on borrower risk and collateral age.
That distinction matters because the CPO rate sheet is not a reflection of your credit alone — it is a reflection of your credit plus Nissan's current willingness to subsidize that specific model year. When the automaker wants to move certified Rogues or Altimas, the CPO tier gets more aggressive; when inventory tightens, the subsidy shrinks. A credit union rate, by contrast, moves with the federal funds rate and the lender's internal cost of capital, not with Nissan's inventory strategy.
How does Nissan CPO eligibility shape the loan itself?
Only vehicles that pass Nissan's certification inspection, fall within model-year and mileage limits set by the program, and come with the CPO limited warranty qualify for NMAC's CPO rate sheet. A used Nissan that fails any of those gates — too many miles, too old, salvage history — is financed as a standard used car, not CPO, even on a Nissan dealer's lot. At Nissan of Everett, that distinction is made at the point of appraisal, not at the finance desk.
Because the loan is tied to a certified vehicle, NMAC can also offer longer terms with less rate penalty than a credit union typically will on an older used car. Nissan of Everett notes that most loan terms fall between 48 and 72 months, which aligns with how CPO portfolios are generally structured across the industry.
How do the two loan types compare side by side?
The table below summarizes the structural differences a shopper in Everett, WA should weigh before signing. Specific rates are not listed here because manufacturer-subvented rates change frequently and vary by credit tier, term, and current program — the Nissan of Everett specials page or a direct quote is the only reliable source for current numbers.
| Attribute | Nissan CPO Financing (NMAC) | Standard Used-Car Loan (Bank/Credit Union) |
|---|---|---|
| Lender type | Captive (manufacturer-owned) | Third-party |
| Vehicle eligibility | Certified Nissan only, 167-point inspection | Any used vehicle meeting lender age/mileage caps |
| Rate mechanism | Subvented tiers tied to inventory programs | Risk-based pricing tied to credit + collateral age |
| Typical term range | 48–72 months | 36–72 months (varies by lender) |
| Warranty bundled | Yes — CPO limited warranty included | No — warranty purchased separately or none |
| Rate stability | Changes with Nissan program cycles | Changes with Fed rate and lender cost of capital |
When does a credit union loan actually beat CPO financing?
A credit union loan can beat NMAC's CPO rate when the subvented program for that model is not running, when the buyer's credit tier is strong enough to earn a credit union's best rate, or when the shopper is buying a non-certified used Nissan that doesn't qualify for CPO pricing anyway. In those cases, the credit union is competing on a level playing field — no manufacturer subsidy is on the table for either side.
The honest answer is that neither channel wins universally. The question is which loan is cheapest on the specific car on the specific day, and that requires running both quotes. Nissan of Everett's finance team works with a number of financial institutions and banks throughout the Edmonds and Marysville, WA area, which lets a single application surface both captive and third-party offers for comparison.
What do Everett, WA shoppers specifically need to factor in?
Washington state sales tax applies to the full purchase price of the vehicle, and Snohomish County shoppers face local tax rates that stack on top of the state base — a meaningful number on a $25,000–$35,000 CPO Nissan. Nissan of Everett offers financing with no down payment in most cases, and can roll taxes, registration, and fees into the financing deal, which matters because those costs affect the total amount financed and therefore the real cost of the loan regardless of rate.
Weather and commute patterns also play a quiet role. Buyers driving I-5 between Everett and Seattle, or crossing US-2 toward Monroe in winter, often prioritize AWD CPO Rogues and Pathfinders — vehicles that tend to retain value well, which is one reason NMAC is willing to subvent rates on them in the first place. Residual-value protection is the economic engine behind the CPO rate advantage.
How does the inventory choice at Nissan of Everett affect which loan applies?
Nissan of Everett sells new Nissan vehicles, Certified Pre-Owned Nissan vehicles, and used cars, trucks, and SUVs. Which rate sheet applies is determined by the car on the lot, not by the buyer's preference — a 2019 Altima with 90,000 miles will not qualify for CPO regardless of how badly a shopper wants the CPO rate, while a certified 2023 Rogue will. Shoppers who care about the rate advantage should filter their search to CPO-eligible inventory first, then compare financing offers second.
For context on current new-vehicle pricing that often anchors CPO value conversations, the 2026 Nissan Rogue, starting at $29,690 (as of October 2026) and the 2026 Nissan Altima, starting at $27,580 (as of October 2026) establish the ceiling against which a two- or three-year-old CPO version is priced. The CPO discount off a comparable new unit is typically where the real savings live — before financing ever enters the conversation.
Ryan in sales, and Milo, the Finance Manager, were beyond helpful from start to finish! They put in extra effort to meet my requests regarding financing and what I wanted for a monthly payment. If you want to shop for a car with honest, no pressure people, you need to head to Nissan of Everett! I drove away in my dream vehicle, I could not be happier! J. Joseph
Frequently asked questions
Is Nissan CPO financing always cheaper than a credit union used-car loan?
No. CPO financing is often cheaper when Nissan is actively running a subvented rate program and the buyer qualifies for the top credit tier, but a strong credit union offer can match or beat NMAC when no subvention is in effect. The only reliable way to know is to run both quotes on the same vehicle on the same day.
What makes a Nissan "Certified Pre-Owned" versus just used?
A Nissan CPO vehicle must pass Nissan's certification inspection, fall within model-year and mileage limits set by the program, and come with the CPO limited warranty. A used Nissan that doesn't meet those criteria is sold and financed as a standard used car, which means it is not eligible for NMAC's CPO rate sheet even on a Nissan dealership lot.
Can taxes and fees be rolled into a CPO loan in Washington?
Yes. Nissan of Everett offers financing with no down payment in most cases and can roll taxes, registration, and fees into the financing deal. This matters in Washington because state and Snohomish County sales tax applies to the full vehicle price, and bundling those costs into the loan is a common way to manage out-of-pocket cash at delivery.
What loan terms are typical for a CPO Nissan?
Most CPO loan terms fall between 48 and 72 months, consistent with the range Nissan of Everett publishes for its financing in general. Longer terms lower the monthly payment but increase total interest paid; shorter terms do the opposite. The right term depends on how long the buyer plans to keep the vehicle and whether they want to stay ahead of depreciation.
Does my credit score matter more with CPO or with a standard used-car loan?
It matters with both, but differently. CPO rate tiers are often compressed — the gap between top-tier and mid-tier credit may be smaller than at a credit union because the manufacturer subsidy flattens the sheet. Credit unions typically price risk more aggressively, which can reward excellent credit more and penalize weaker credit more than NMAC's CPO program will.
Should I get pre-approved by my bank before visiting a dealer?
Yes — a pre-approval gives a benchmark rate to compare against the dealer's financing offer. If the CPO rate beats the pre-approval, take the CPO rate; if the pre-approval wins, use it. Nissan of Everett's finance team works with multiple lenders across the Edmonds and Marysville area, so a dealer-side application can surface competing offers in one step.
The bottom line for Everett, WA shoppers
Nissan CPO financing and a standard used-car loan are not the same product priced differently — they are two different products with two different pricing logics. CPO rates are a manufacturer tool; used-car rates are a lender's risk calculation. The right choice depends on the specific vehicle, the current NMAC program, and the shopper's credit profile on the day the paperwork is signed.
Readers in Everett, WA who want to compare a CPO offer against outside financing on a specific Nissan can reach Nissan of Everett at (425) 347-5763 or https://www.nissanofeverett.com to request a quote and run the numbers both ways.