Co-Signer on a Nissan Car Loan in Everett, WA
How adding a co-signer to a Nissan auto loan works in Washington: lender rules, co-signer vs. co-borrower, liability, and what to bring to the finance office.
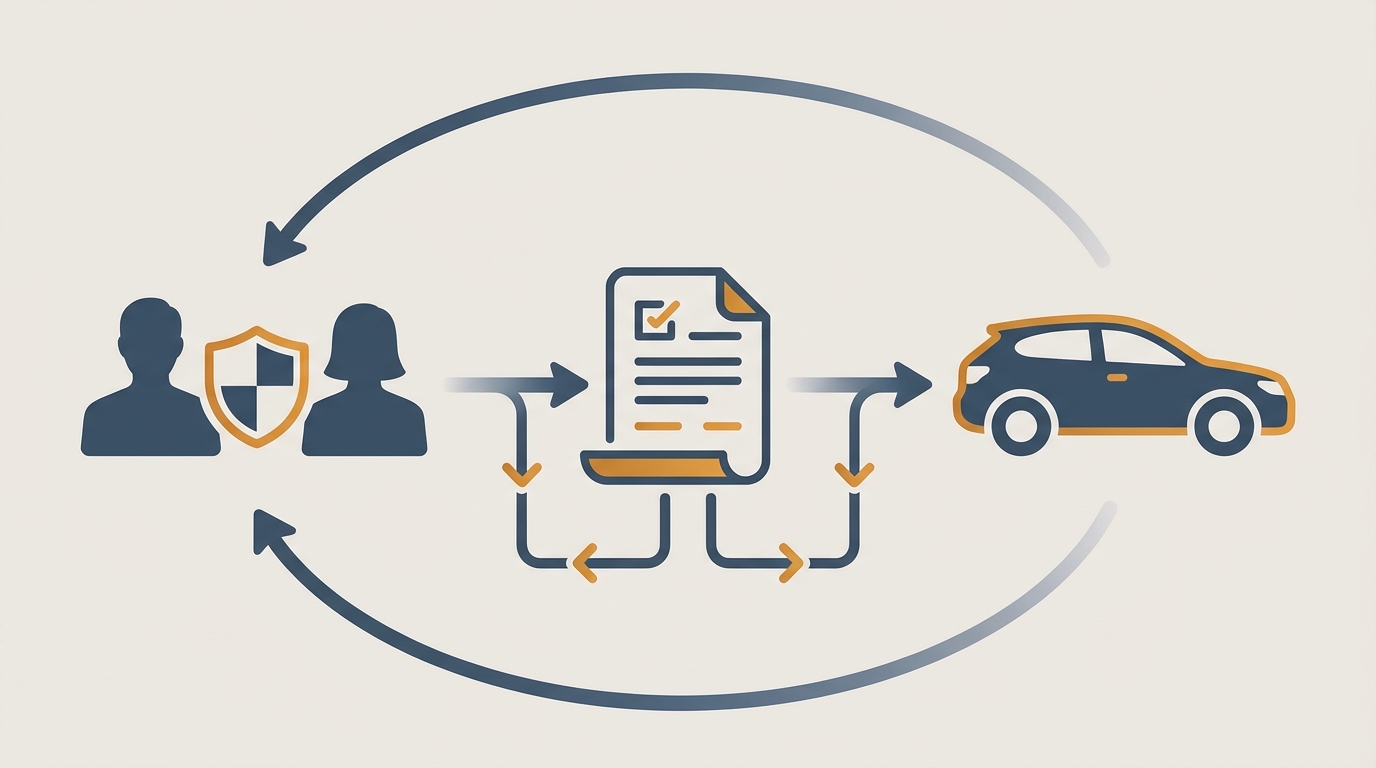
Adding a co-signer to a Nissan auto loan in Washington means a second qualified adult signs the loan contract and agrees to repay the debt if the primary borrower does not. Washington State does not require a co-signer by statute, and it does not set credit-score, income, or relationship rules — whether a co-signer is allowed, and who qualifies, is each lender's underwriting decision. Once both parties sign, the contract and federal lending laws govern what happens next.
What does a co-signer actually do on a Washington auto loan?
A co-signer is a second person who signs the loan agreement and becomes legally responsible for covering any payments the primary borrower misses. If the primary borrower defaults, the co-signer becomes liable for all remaining payments and fees specified in the loan agreement. A co-signer does not automatically acquire ownership of the vehicle — title is set by the purchase paperwork, not the loan.
That distinction matters in Everett. A parent co-signing for a college student commuting down I-5 to Edmonds Community College, or a spouse strengthening a partner's application on a new 2026 Nissan LEAF, starting at $29,990 (as of October 2026), is adding financial backing to the loan — not putting their name on the car. Both parties must sign the loan documents if the lender approves the deal.
Is a co-signer the same as a co-borrower in Washington?
No. A co-signer guarantees the debt but has no ownership rights to the vehicle. A co-borrower shares ownership of the financed vehicle and is equally responsible for repaying the loan. The practical difference is whose name goes on the Washington title and registration, and who has the legal right to drive, sell, or trade the car.
Families often choose between the two based on who will actually use the vehicle. A grandparent helping a first-time buyer qualify may prefer co-signer status to stay off the title; a married couple buying a 2026 Nissan Rogue, starting at $29,690 (as of October 2026) as a shared household vehicle typically goes the co-borrower route so both names appear on the title.
Does Washington State require a co-signer on a Nissan loan?
Washington State does not impose a statutory requirement that auto loans carry a co-signer, and it does not set minimum credit score, income, or relationship criteria for one. Per guidance from the Washington State Office of the Attorney General, whether a co-signer is required and how that person is evaluated is a lender underwriting decision. Some lenders, in fact, do not allow co-signers on auto loans at all.
This is why the answer at the finance desk depends on which bank or credit union the deal is placed with. Nissan of Everett's finance team works with a number of financial institutions and banks throughout the Edmonds and Marysville, WA area, which gives the office room to shop an application that may need a co-signer to one lender versus another.
What federal rules protect co-signers?
Two federal frameworks apply directly to auto-credit transactions involving co-signers. The Truth in Lending Act (TILA) requires lenders to disclose credit terms — APR, finance charge, payment schedule, and total cost — to all parties on the loan. The Equal Credit Opportunity Act (ECOA) governs how creditors decide applications and whether they can request additional applicants such as co-signers.
How does the co-signer process work inside the Nissan of Everett finance office?
Mechanically, adding a co-signer means submitting a joint credit application so the lender can evaluate both parties together. The underwriter looks at combined income, debt-to-income ratio, and credit history, then returns an approval tied to a specific lender's program. Both signatures are required on the final loan documents for the approval to fund.
Nissan of Everett offers financing with no down payment in most cases, and can roll taxes, registration, and fees into the financing deal, which can change the math on whether a co-signer is needed at all. Loan terms at the dealership fall well within the one-to-seven-year range typical for auto loans.
Documentation a co-signer should expect to bring:
- Government-issued photo ID
- Proof of income (recent pay stubs or tax returns for self-employed applicants)
- Proof of residence
- Social Security number for the credit pull
How does a co-signer affect loan approval and rate?
A qualified co-signer can help a borrower qualify for an auto loan, and may help secure a lower interest rate — even in cases where the primary borrower would have qualified alone. The lender is pricing risk; a stronger combined credit profile usually produces better terms.
When comparing offers, Washington's Attorney General guidance advises shoppers to weigh the APR, the down payment, the approximate monthly payment, the number of payments, and the total cost of the loan. Those disclosures apply equally to the co-signer, who is on the hook for the same numbers. Long-term loans carry a specific trap: stretching payments out can leave a borrower upside down if they plan to trade the vehicle in after three or four years, because the loan balance may exceed the car's worth.
Co-signer vs. co-borrower at a glance
| Attribute | Co-signer | Co-borrower |
|---|---|---|
| Signs the loan agreement | Yes | Yes |
| Liable for missed payments | Yes | Yes |
| Liable at default for full balance | Yes | Yes |
| Ownership interest in the vehicle | No | Yes (shared) |
| Name on Washington title | No | Yes |
| Credit impact of the loan | Yes | Yes |
What does the Everett experience actually look like?
Nissan of Everett has been part of the Everett community for 20 years, and its finance office handles joint applications — including co-signer and co-borrower structures — as part of routine business. The dealership sells new Nissan vehicles, Certified Pre-Owned Nissan vehicles, and used cars, trucks, and SUVs, so co-signer scenarios range from a first-time buyer financing a 2026 Nissan Sentra, starting at $22,990 (as of October 2026) to a household adding a second driver to a 2026 Nissan Pathfinder, starting at $39,990 (as of October 2026).
I worked with Blake, James, Tegan and Milo on getting a car lease that I could afford. I loved the entire experience. They went above and beyond to help me get an affordable car lease. The people were extremely nice, transparent, respectful and professional. I highly recommend coming here before deciding on your car.
Frequently asked questions
Can a co-signer be removed from a Nissan auto loan later?
Removing a co-signer requires the lender's agreement, and typically means either refinancing the loan in the primary borrower's name alone or using a release provision if the contract includes one. Washington law does not mandate a release option — it is a contract term. The primary borrower will usually need to show improved credit and income to qualify solo before a lender signs off.
Does a co-signer's credit score go up or down from an auto loan?
Both outcomes are possible. On-time payments can help a co-signer's credit by adding a positive installment account to their history. Missed payments, default, or repossession, however, appear on the co-signer's credit report just as they do on the primary borrower's, because the co-signer is legally responsible for the debt.
Can a Washington co-signer live out of state?
Washington State does not prohibit out-of-state co-signers on auto loans — it is a lender underwriting decision. Many banks and credit unions accept them, though some require the co-signer to live in the same state or lending footprint. The finance office confirms this with the specific lender before the application is submitted.
What happens if the primary borrower stops paying?
The co-signer becomes legally responsible for covering any payments the primary borrower misses, and at default is liable for all remaining payments and fees in the loan agreement. The lender can pursue the co-signer directly without first exhausting collection against the primary borrower, unless the contract says otherwise. Whether a deficiency balance remains after a repossession and sale depends on contract terms and applicable law.
Does adding a co-signer change the down payment or loan term?
It can. A stronger combined application may allow a lender to approve a lower down payment, a longer term, or a better APR. Washington auto loan terms commonly run anywhere from one to seven years; most loans written through Nissan of Everett fall between 48 and 72 months.
Can a co-signer insist on being added to the title?
No — signing the loan does not grant ownership rights to the vehicle. A party who wants to be on the title must be structured as a co-buyer on the purchase paperwork, which also makes them a co-borrower on the financing. This is a decision to make before signing, not after.
Working through it in Everett, WA
A co-signer arrangement is a serious financial commitment for both parties, and the rules that govern it come from the contract and federal lending law — not from a Washington statute dedicated to the topic. Readers in Everett, WA who want to walk through a specific scenario, pre-qualify, or map out whether a co-signer or co-borrower structure fits their situation can reach Nissan of Everett at (425) 347-5763 or https://www.nissanofeverett.com to speak with the finance team at 10500 Highway 99.